The short answer
A few weeks after you file, an envelope from the IRS arrives. The top corner says CP14, and the big line says “Amount due.” Maybe you knew you’d owe and couldn’t pay it all in April, or maybe it’s a complete surprise.
A CP14 notice is the IRS’s first bill: it says you have unpaid tax on a return, plus any penalty and interest so far, and asks you to pay by the due date printed on it, usually about three weeks from the notice date. If you can’t pay it all, a payment plan stops the letters that follow. It’s the cheapest point in the whole process to deal with a balance.
How worried to be
It's a real bill, but the first and cheapest one. Pay by the due date or set up a payment plan, and the letters stop here.
When your reply is due
The IRS's usual window is 21 days from the notice date. Enter the date to see yours.
The IRS's CP14 page says to pay by the due date on the notice. In the IRS's own sample CP14, that date was 21 days after the notice date. Your notice prints yours, and that's the one that counts.
CP14, decoded: tap any part of the letter
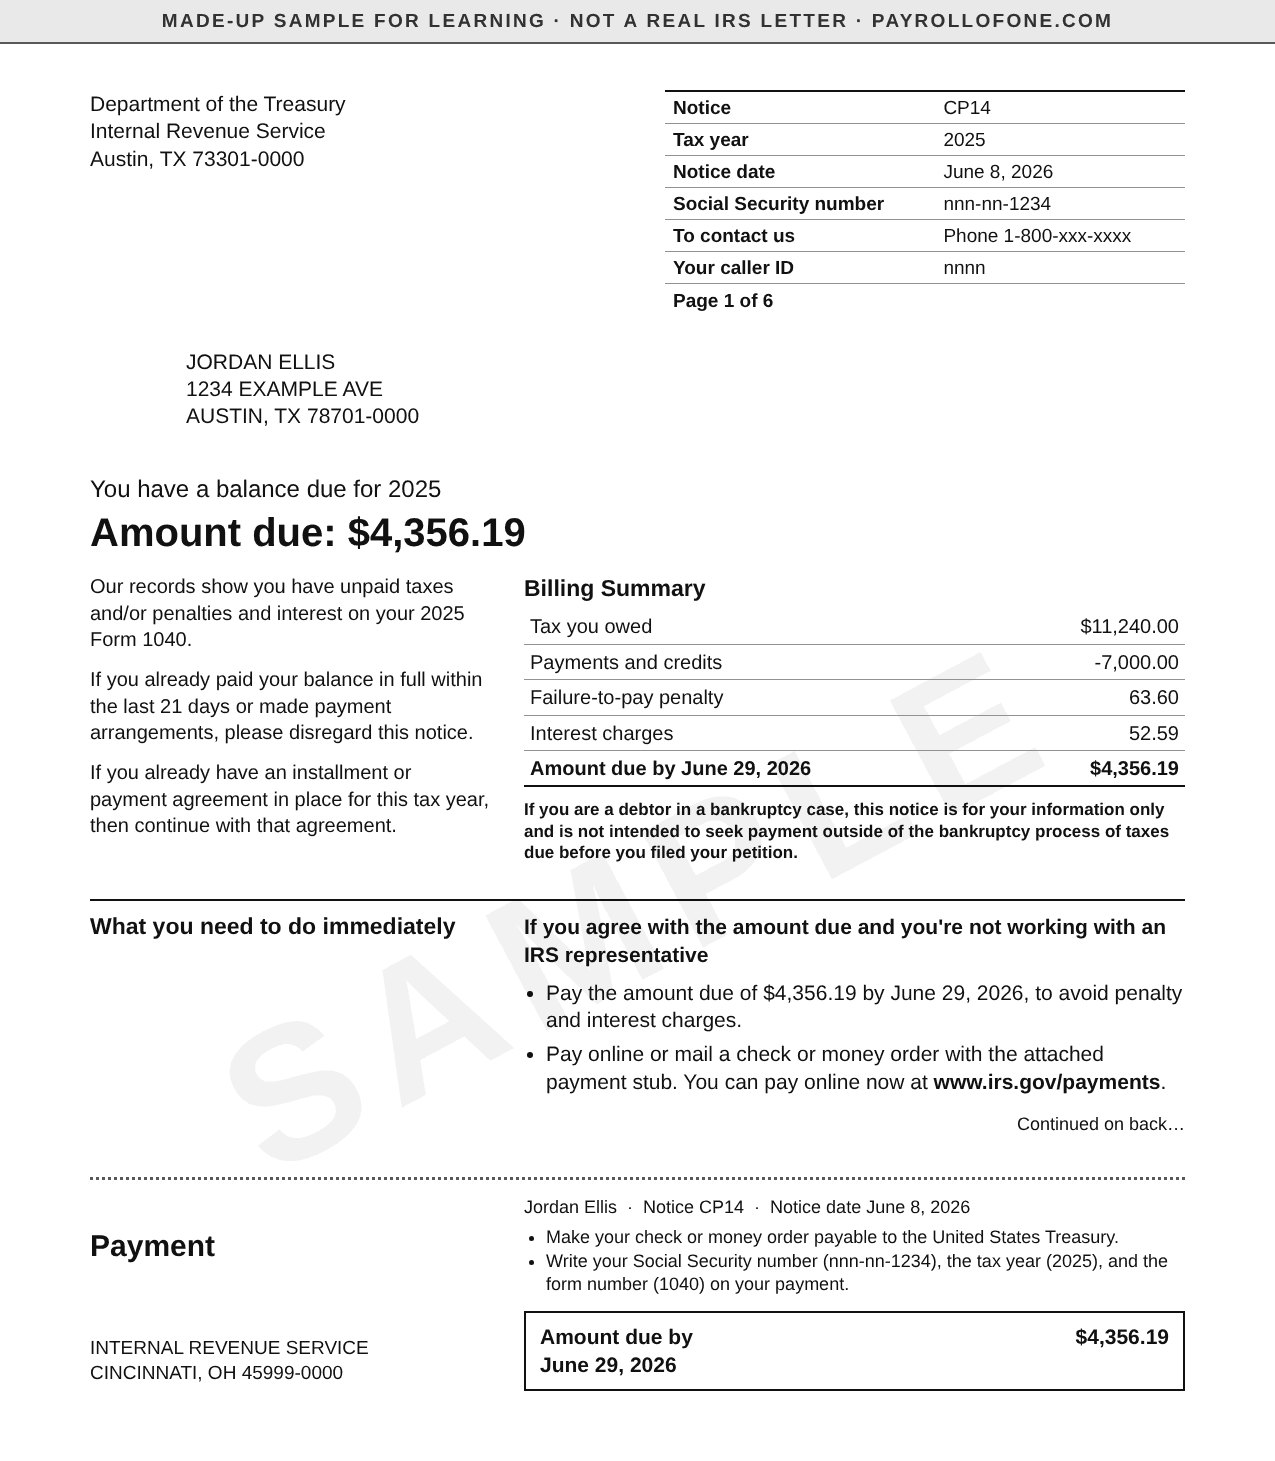
The IRS no longer shows sample letters on its notice pages, so we rebuilt this one from its older official sample, with made-up details. Every part has a plain-English note. Yours will have different numbers but the same parts in about the same places.
Tap any part of the letterHover over any part of the letter to see what it means. Click a part to pin its note open so you can use the links. to see what it means. Our made-up example: Jordan Ellis, a freelance photographer, filed a 2025 return on time but couldn't pay the last $4,240.
Swipe sideways to see the whole letter.
Every part, in plain English
Notice The notice code
CP14 is the IRS's first bill for unpaid tax on a return. If it isn't paid or arranged, reminders follow: CP501, then CP503, then CP504, the notice of intent to levy. Each one costs a little more.
ExampleType CP14, CP501 or CP503 into our lookup and you land on this page.
Good to knowGot a CP14C instead? That version goes to people in a federally declared disaster area, and the IRS says the extra time to pay is automatic.
Tax year Which return the balance is from
The year of the return with the unpaid balance. It's often the return you filed this spring, but a bill that follows a CP2000 or another change to an older return can be for an earlier year.
ExampleJordan's bill is for the 2025 return, filed on time in April 2026.
Good to knowPull out that year's return and your payment records before you read further.
Notice date The date that starts the clock
The due date in the billing summary counts from this date, not from the day the letter reached your mailbox. In the IRS's own sample CP14, the due date was 21 days after the notice date.
ExampleJordan's notice is dated June 8, 2026, and the due date is June 29, 2026, 21 days later.
Good to knowEnter this date in the box above the letter to see the date 21 days later. The date printed on your notice is the one that counts.
Your number Social Security number
The IRS prints your taxpayer ID on the notice. Our sample hides it. A real bill with your name or number wrong is worth a call to the IRS before you pay anything.
Good to knowNot sure a bill is real? The IRS starts contact by mail, and payment always goes to the United States Treasury, never to a person or by gift card. You can also check for the notice in your IRS Online Account.
To contact us The number to call if the bill looks wrong
Call this number if you disagree with the amount or think a payment is missing. The IRS's CP14 page says to have your paperwork ready, such as cancelled checks or an amended return. If you don't call, the notice says the IRS will assume you agree.
ExampleIf Jordan had sent a payment that isn't showing, this is where to start, with the bank record in hand.
Good to knowThe IRS says wait times are shorter Wednesday through Friday, and a payment plan can be set up online without calling.
Headline Amount due
Everything the IRS says you owe on this return right now: the unpaid tax plus the penalty and interest added so far. A CP14 is a bill, not a proposal, so there's no form to sign if you agree. You pay it.
ExampleJordan's amount due is $4,356.19.
Good to knowIf the amount is right but more than you can pay at once, a payment plan is the usual answer. It also stops the reminder letters.
Already paid? If you paid or set up a plan recently
Bills cross in the mail. If you paid the full balance within the last 21 days or made payment arrangements, the notice says to disregard it. If you already have a payment plan for this tax year, keep making those payments.
ExampleIf Jordan had paid on June 1, the June 8 notice could still arrive, and the payment would already be on file.
Good to knowThe notice points to irs.gov/balancedue to check your current balance and payment history.
Tax and payments Tax you owed, minus what you paid
The total tax on your return, then the payments and credits the IRS has on file: quarterly estimated payments, withholding and anything paid with the return. The difference is the unpaid tax that started this bill.
ExampleJordan's 2025 tax was $11,240. Jordan paid $7,000 in four quarterly payments, leaving $4,240 unpaid. Those payments matched Jordan's full 2024 tax, which is why there's no estimated tax penalty line.
Good to knowIf a payment you made is missing here, call the number on the notice with proof of the payment.
Penalty Failure-to-pay penalty
The late-payment penalty: 0.5% of the unpaid tax for each month or part of a month it stays unpaid, up to 25% in total. It runs from the return's due date, and the IRS charges a full month even if you pay partway through one.
ExampleJordan's June 29 due date falls in the third penalty month since April 15: $4,240 × 1.5% = $63.60.
Good to knowNew for 2025 returns: if you filed and paid on time for the three years before, the IRS says it won't charge this penalty at all and sends a letter saying so. Our sample assumes Jordan doesn't have that history.
Interest Interest charges
Interest on the unpaid tax from the return's due date, compounded daily at the IRS's rate for each quarter: 6% a year from April to June 2026 and 7% from July. The IRS's CP14 page says you aren't charged more interest if you pay the full amount by the date on the notice.
ExampleApril 15 to June 29 is 75 days of interest on $4,240 at 6%, compounded daily: $52.59.
Good to knowBy law, the IRS can't remove interest just because you had a good reason to pay late. Interest on a penalty drops only if that penalty is removed.
Amount due by Your pay-by date
The date to pay the full amount. After it, interest and the late-payment penalty keep adding up on whatever is unpaid, and the reminder letters start.
ExamplePaying $4,356.19 by June 29, 2026 closes out Jordan's 2025 balance.
Good to knowCan't pay it all? A short-term plan of 180 days or less has no setup fee. If you filed on time, the late-payment penalty drops to 0.25% a month while an approved plan is in place.
What to do What you need to do immediately
The IRS's steps for a CP14: read the notice, pay by the due date, set up a payment plan if you can't pay it all, and call if you disagree. Paying online gives you instant confirmation.
ExampleJordan agrees with the bill, so it's a payment: online at irs.gov/payments, or a check with the stub below.
Good to knowThese steps are for people who agree and aren't already working with an IRS representative. If you are, start with that person.
Payment stub The tear-off stub
If you pay by mail, this part goes in the envelope with your check or money order, so the payment lands on the right account and year. Make the check payable to the United States Treasury and write your Social Security number, the tax year and the form number on it.
ExampleJordan's check would carry the Social Security number, 2025 and 1040.
Good to knowPaying online? You don't need the stub. Keep the notice with your 2025 tax records either way.
What a CP14 means
The IRS’s own explanation is one sentence: you got this notice because you owe money on unpaid taxes. The bill shows how that balance adds up, so you can check it against your own records.
- Tax you owed: the total tax on the return.
- Payments and credits: your quarterly estimated payments, any withholding and anything you paid when you filed.
- Failure-to-pay penalty: 0.5% of the unpaid tax for each month or part of a month since the return’s due date.
- Interest: charged daily on the unpaid tax from the due date, at 7% a year for most of 2026.
For freelancers, a CP14 often means the quarterly payments fell short of the year’s tax and the rest wasn’t paid with the return. Say you earned more in 2025 than in 2024, like Jordan in our sample. Jordan’s four payments of $1,750 matched the 2024 tax, which avoided the estimated tax penalty, but left $4,240 of 2025 tax to pay in April. A CP14 can also follow a change to an older return, such as an agreed CP2000.
What to do, in the IRS’s order
The IRS’s CP14 page lists four steps. Here they are, with what each one looks like in practice.
- Read the notice carefully. Check the tax year, then compare the payments line with your bank records. A payment that’s missing is the most important thing to catch.
- Pay by the due date on the notice. Pay online at irs.gov/payments for instant confirmation, or mail a check to the United States Treasury with the payment stub.
- Make a payment plan if you can’t pay it all. Pay what you can now and set up a plan for the rest, online for most people.
- Call if you disagree. Use the number on the notice, with cancelled checks or other records ready. If you don’t contact the IRS, it assumes you agree.
Here’s what most people in your spot do the day a CP14 arrives: check the payments line against your records, put the due date on your calendar, and decide that evening between paying in full and setting up a plan. Waiting is the one choice that always costs more.
If you can’t pay it all
Not having the money is common, and the IRS has standard options for it. Here’s how they compare in 2026.
| Option | Best for | Setup fee | Keep in mind |
|---|---|---|---|
| Pay in full by the due date | Anyone who can | None | Nothing more is added |
| Short-term plan | Paying it off within 180 days | None | Interest and the late-payment penalty until it’s paid |
| Long-term plan (installment agreement) | Monthly payments over a longer stretch | Lowest with direct debit set up online | Interest, and a late-payment penalty cut to 0.25% a month if you filed on time |
| Offer in compromise | People who truly can’t pay the full amount | Application fee, unless you qualify as low income | Accepted only when the IRS agrees you can’t pay in full, the debt may be wrong, or paying would be unfair |
Say Jordan can pay $2,000 now. Paying that right away and putting the rest on a short-term plan costs no setup fee and shrinks the balance that interest is charged on. Here’s how to set up an IRS payment plan, step by step. Our IRS penalty calculator compares what each way of paying adds, cheapest first.
What happens if you ignore it: CP501, CP503 and CP504
A CP14 doesn’t go away on its own. If the balance stays unpaid and there’s no plan, the IRS sends reminders in a set order, and each one adds more interest and penalty.
If a balance stays unpaid
The IRS's letters, in order
- CP14First bill: you oweYou are here
- CP501Reminder
- CP503Second reminder
- CP504Notice of intent to levy
- LT11 or 1058Final notice, with the right to a hearing
Each letter has its own date to act by. Paying the balance, or setting up a payment plan with the IRS, ends the sequence. Sources: IRS Publication 594, The IRS Collection Process, and the IRS's page for each notice.
Here’s what each of the next letters says, in the IRS’s own words.
| Letter | What it is | What the IRS says can happen next |
|---|---|---|
| CP501 | A reminder that the balance is still unpaid, with a new due date (22 days out in the IRS’s sample) | The IRS can file a Notice of Federal Tax Lien, a public notice to your creditors that can affect your credit |
| CP503 | The second reminder, with a new due date (21 days out in the IRS’s sample) | A Notice of Federal Tax Lien, if one isn’t filed already |
| CP504 | The notice of intent to levy, with the amount due immediately | The IRS can take a state tax refund after 30 days, then move toward wages, bank accounts and other property |
A CP501 or CP503 works just like a CP14: read it, pay by its due date or set up a plan, and call if you disagree. Both also mention the Collection Appeals Program, a way to appeal before the IRS takes collection action.
In our made-up example, Jordan’s $4,356.19 grows to $4,502.41 by the October CP504. That’s $146.22 for waiting four months, and the penalty rate can double after that letter. Here’s what a CP504 says, part by part.
When to get help
Most people handle a CP14 themselves: it’s a bill, and paying it or setting up a plan takes a few minutes online. Help earns its cost when the balance is large, covers several years, or you think the bill is wrong and the records are messy.
If you can’t afford a professional, the Taxpayer Advocate Service and Low Income Taxpayer Clinics are free options the IRS lists. Here’s when a tax pro is worth it, and what one costs. To keep the next April from landing the same way, here’s how quarterly estimated taxes work.
FAQ
Is a CP14 notice serious?
It’s a real bill, but it’s the first and mildest one. Paying it or setting up a payment plan by the due date ends the matter. It gets more serious only if it’s ignored.
How long do I have to pay a CP14?
Until the due date printed in the billing summary. In the IRS’s own sample, that was 21 days after the notice date. The date on your notice is the one that counts.
Will I be charged more interest if I pay by the due date?
No. The IRS’s CP14 page says you aren’t charged more interest if you pay the full amount by the date on the notice. Interest builds on anything unpaid after that.
I already paid. Why did I get a CP14?
Payments and notices cross in the mail. The notice says to disregard it if you paid in full in the last 21 days or set up a plan. If an older payment is missing, call the number on the notice with proof.
Can the penalty be removed?
Often, yes. The IRS can remove the late-payment penalty for a good reason, or under First Time Abate if your recent record is clean. For 2025 returns onward, the IRS says it won’t charge the penalty at all for people with three clean prior years. Interest stays, apart from interest on a removed penalty.
What’s the difference between CP14, CP501 and CP503?
CP14 is the first bill. CP501 is the first reminder and CP503 the second, each with a new due date and a bit more interest and penalty. After those comes the CP504, the notice of intent to levy. A balance that’s still open a year later can also bring a yearly reminder, the CP71.
How do I know a CP14 is really from the IRS?
The IRS starts contact by mail, and payment always goes to the United States Treasury. You can check the notice in your IRS Online Account, or call the IRS at a number listed on irs.gov. Our IRS letter decoder explains other codes too.
Sources
- IRS: Understanding your CP14 notice
- IRS: Understanding your CP501 notice
- IRS: Understanding your CP503 notice
- IRS: Publication 594, The IRS Collection Process (PDF)
- IRS: Failure to pay penalty
- IRS: Administrative penalty relief
- IRS: Payment plans, installment agreements
- IRS: Quarterly interest rates
The letter above is a made-up sample for learning, laid out like the IRS’s own CP14. It isn’t a real notice and nothing on this page reads or answers yours. Interest uses the IRS’s 2026 rates (6% in the second quarter, 7% the rest of the year). General education, not tax advice.