The short answer
You set up a payment plan with the IRS and it was going fine. Then a slow month came, a payment or two slipped, and now there’s a notice with CP523 in the corner and a headline about terminating your installment agreementThe IRS name for a long-term payment plan: you pay what you owe in monthly amounts, with interest and a reduced penalty..
A CP523 notice means your IRS payment plan is in default: the IRS intends to end the agreement 30 days from the notice date and then move to collect the whole balance, including by levy. Paying the past due amount before that date, or calling the IRS to reinstate or restructure the plan, can keep it in place. It’s urgent, and it’s usually fixable if you act within the 30 days.
How worried to be
The payment plan that keeps collection away is about to end. Paying the missed amount, or calling the IRS, before the termination date can keep the plan in place.
When your reply is due
The IRS's usual window is 30 days from the notice date. Enter the date to see yours.
The IRS's CP523 page says to contact it as soon as possible but no later than 30 days from the notice date. The notice says the installment agreement will be terminated 30 days from the notice date if the past due amount isn't paid.
CP523, decoded: tap any part of the letter
The IRS no longer shows sample letters on its notice pages, so we rebuilt this one from its older official CP523 sample, with made-up details. Yours will have different numbers but the same parts in about the same places.
Tap any part of the letterHover over any part of the letter to see what it means. Click a part to pin its note open so you can use the links. to see what it means. Our made-up example: Jordan Ellis, a freelance photographer, has a $275-a-month payment plan for a 2024 balance and missed the June and July payments.
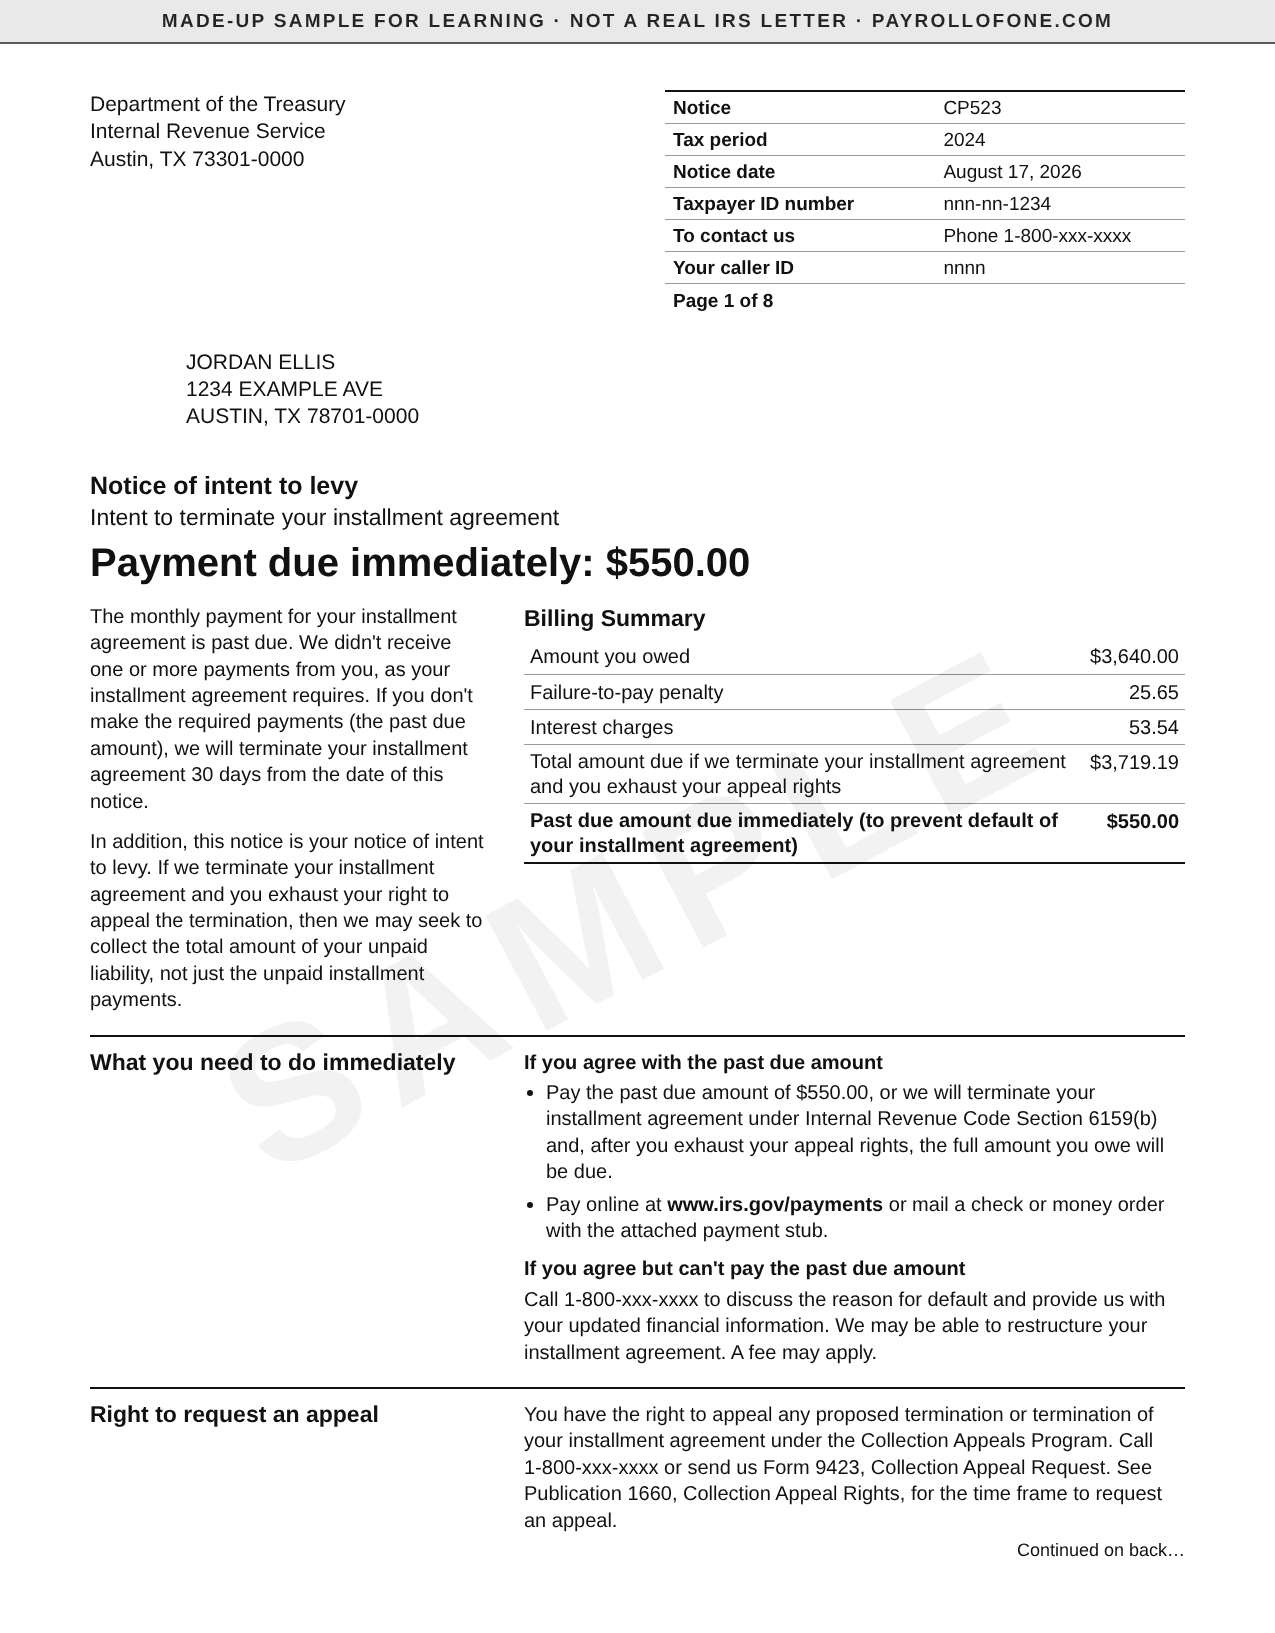
Swipe sideways to see the whole letter.
Every part, in plain English
Notice The notice code
CP523 tells you the IRS intends to end your installment agreement, the formal name for a payment plan, and to levy, because the agreement is in default. The IRS's page says the same notice can also come as CP523 (SP) or CP623.
ExampleType CP523 into our lookup and you land on this page.
Tax period Which balance the plan covers
The tax year of the balance in your payment plan. The IRS's older sample says you get a notice for each tax period you owe, but the past due amount only has to be paid once.
ExampleJordan's plan covers the 2024 return, so this notice is for 2024.
Good to knowA plan that covers two years can mean two CP523s in one week. Read the past due amount before you pay twice.
Notice date The date the 30 days count from
The notice says the agreement will be terminated 30 days from this date unless the past due amount is paid. The IRS's CP523 page says to contact it no later than 30 days from the notice date.
ExampleJordan's notice is dated August 17, 2026, so the termination date is September 16, 2026.
Good to knowEnter this date in the box above the letter to see your own 30-day date.
To contact us The number to call right away
Call to see if the agreement can be reinstated, to talk about why you defaulted, or if you disagree. The IRS's page asks people who have already fixed the problem to call anyway, so its records show it and it can reinstate the agreement.
ExampleIf Jordan already paid the $550 on August 20, a call confirms the IRS has it.
Good to knowIf you can't pay what's past due, the IRS says to call and give updated financial information. It may be able to restructure the plan.
Two warnings Intent to terminate, and intent to levy
Two things in one notice. The IRS intends to end the payment plan, and the notice counts as your Notice of Intent to Levy under Internal Revenue Code section 6331(d). Once the plan ends and appeal rights run out, the IRS can move to collect the whole balance.
ExampleJordan's plan has kept the IRS from levying since it began. This notice says that protection is about to end.
Good to knowThe older IRS sample says that after termination, the IRS can levy most property only if it has already sent you a Collection Due Process notice, like an LT11. Without one, it can still take a state tax refund.
Payment due Payment due immediately
Just the missed payments, not the whole balance. Paying this amount before the termination date is how the IRS says to keep the agreement from being terminated.
Example$550.00: two missed payments of $275.
Good to knowPaying online gives instant confirmation, which matters with a deadline this close.
Why you got it The reason for the default
The IRS's page says the notice tells you why it's taking this action. Here it's missed monthly payments. The IRS also says a plan stays in good standing only if you file all required returns on time and pay new taxes in full, so a new unpaid balance can trigger it too.
ExampleJordan's reason is the simplest one: the June 28 and July 28 payments never arrived.
Good to knowThe IRS applies your future refunds to the debt until it's paid, and says to keep making scheduled payments even when it does.
Amount you owed What's left on the plan
The remaining balance on your agreement after the payments you've made: tax, penalty and interest charged up to your last payment.
Example$3,640.00 was left after Jordan's May 28 payment, $3,420 of it unpaid tax.
Penalty Failure-to-pay penalty
For people who filed on time, the late-payment penalty drops from 0.5% to 0.25% of the unpaid tax a month while an approved plan is in effect. That lower rate applies only during the plan.
ExampleThree months at 0.25% on Jordan's $3,420 of unpaid tax: $25.65.
Good to knowKeeping the plan alive keeps the lower rate. That's part of what's at stake here.
Interest Interest charges
Interest keeps compounding daily on the balance during a payment plan, at the IRS's rate for each quarter: 6% a year from April to June 2026 and 7% from July.
Example$53.54 on Jordan's $3,640 balance in the 81 days since the last payment.
Good to knowPaying more than the minimum shortens the plan and cuts the interest.
If terminated Total due if the plan ends
What the IRS can try to collect in full if it terminates the agreement and you've used up your appeal rights: the whole remaining balance, not just the missed payments.
Example$3,719.19 for Jordan, against $550 to catch up now.
Good to knowThe IRS says it can't levy until 30 days after it terminates a plan, and not while a timely appeal of the termination is pending.
Past due Past due amount
The amount that cures the default. It's the same number as the headline, shown here next to the full balance so you can compare them.
Example$550.00, due immediately.
Good to knowYou may have to pay a fee to reinstate the plan, or pay any new tax balance in full, says the IRS's CP523 page.
What to do Pay, or call to restructure
If you agree, pay the past due amount before the termination date. If you agree but can't pay it, call to discuss the reason for the default and give updated financial information. The IRS may be able to restructure the plan, and a fee may apply.
ExampleJordan could pay $550 online, or call to lower the monthly payment if $275 no longer works.
Good to knowThe IRS lists "reinstate after default" among the changes you can make to a plan in your Online Account. In 2026, changing a plan online costs $6, against $89 by phone, mail or in person.
Appeal Collection Appeals Program
You can appeal a proposed termination under the Collection Appeals Program by phone or with Form 9423. Publication 1660 says to ask within 30 days of the notice date, and that the right continues for 30 more days after a termination. The decision is binding and can't be taken to court.
ExampleJordan agrees the payments were missed, so an appeal wouldn't help here.
Good to knowIf you appeal before the termination takes effect, Publication 1660 says you can't appeal the same decision again once it does.
What a CP523 means
The IRS’s page says it plainly: you have defaulted on your installment agreement, and the IRS intends to terminate it and seize (levy) your assets. The notice also counts as a formal Notice of Intent to Levy under Internal Revenue Code section 6331(d).
The notice tells you why the plan is in default. These are the plan rules the IRS lists, and breaking any of them can lead here.
- Pay at least the monthly payment when it’s due. A missed or short payment is the reason in our sample.
- File every required tax return on time.
- Pay new taxes in full and on time. For a freelancer, that includes the quarterly estimated payments for the current year.
- Keep paying when the IRS takes a refund. Your refunds go to the debt, but the IRS says to make every scheduled payment anyway.
Say you’re like Jordan in our sample, paying $275 a month on a 2024 balance. Two missed payments mean $550 is past due, and that $550 is what stands between keeping the plan and owing the full $3,719.19 right away.
What to do, in the IRS’s order
The IRS’s CP523 page lists three steps. All of them come before the termination date on the notice.
- Make your payment before the termination date. Paying the past due amount is how the IRS says to keep the agreement from being terminated. Paying online gives instant confirmation.
- Contact the IRS right away about reinstating the plan. You may have to pay a fee to reinstate it, or pay any new tax balance in full. If the monthly amount no longer works, the IRS may be able to restructure the plan once you give it updated financial information.
- Read the notice carefully. It explains the reason for the default and what to do now.
Already fixed it? The IRS still asks you to call, so its records show the payment and it can reinstate the agreement. Individuals can also make some changes in their IRS Online Account, which lists reinstating after default among them. In 2026, the IRS charges $6 to revise a plan online and $89 by phone, mail or in person.
Here’s what most people in your spot do the day a CP523 arrives: pay the past due amount online if you can, then call or log in to confirm the plan is back in good standing. If the monthly payment was the problem, ask for one you can keep. Here’s how IRS payment plans work, and what each one costs.
What happens if the plan is terminated
If the 30 days pass with no payment or call, the IRS says it will terminate the agreement and begin collection action. Here’s what that opens up.
- The whole balance comes due. Once your appeal rights are used up, the IRS can collect everything you owe, not just the missed payments.
- A levy, after a waiting period. The IRS can’t levy until 30 days after it terminates a plan, or while a timely appeal is pending. The IRS’s older sample says that after that, it can levy most property only if it has already sent a Collection Due ProcessYour right to a hearing with the IRS Independent Office of Appeals before most levies. You ask for it on Form 12153 within 30 days of the final notice. notice, like an LT11. Without one, it can still take a state tax refund.
- A tax lien. The IRS can file a Notice of Federal Tax LienA public notice the IRS files to tell your creditors it has a legal claim against your property for unpaid tax. It can make it harder to borrow, sell property or get credit., which can make it hard to sell or borrow against property and may appear on your credit report.
- Higher costs. The reduced 0.25% monthly late-payment penalty applies only while an approved plan is in effect.
The termination date is the real deadline. Keeping a plan in good standing is much simpler than asking for a new one after the IRS has ended it.
Appealing the termination
If you think the IRS got it wrong, the Collection Appeals Program lets you appeal a proposed or actual termination. Call the number on the notice first, and if that doesn’t settle it, ask for the appeal. Here’s the timeline Publication 1660 gives.
| Step | What Publication 1660 says |
|---|---|
| How to ask | By phone, unless the notice came from a revenue officer. Then in writing, preferably on Form 9423 |
| Deadline | Within 30 days of the notice date. After a termination, the right to appeal continues for 30 more days |
| Levy while it’s pending | None, if you appeal within the 30 days after termination, unless collection is in jeopardy |
| The decision | Binding on you and the IRS. You can’t take it to court |
| One chance | If you appeal before the termination takes effect, you can’t appeal the same decision again once it does |
An appeal suits a dispute, such as a payment the IRS didn’t credit. If the payments really were missed, paying or restructuring is usually the faster fix.
When to get help
Most people resolve a CP523 with one payment or one call. Help is worth it when you can’t make any payment right now, the plan covers several years, or the IRS has already terminated it and a final notice has arrived.
The Taxpayer Advocate Service helps for free when a tax problem is causing financial hardship, and Low Income Taxpayer Clinics can represent you if you qualify. Here’s when a tax pro is worth it, and what one costs. To keep new tax from tripping the plan, here’s how quarterly estimated taxes work.
FAQ
How long do I have after a CP523?
The IRS’s page says to contact it as soon as possible but no later than 30 days from the notice date. The notice says the agreement will be terminated 30 days from that date if the past due amount isn’t paid.
Can I reinstate my installment agreement after a CP523?
It may be possible. The IRS’s page says to contact it right away to see if the agreement can be reinstated, and that you may have to pay a fee or pay any new tax balance in full.
Will the IRS levy my bank account right away?
No. The IRS can’t levy until 30 days after it terminates a plan, and not while a timely appeal of the termination is pending. For most property it also needs to have sent a Collection Due Process notice, like an LT11.
Why did I get two CP523 notices?
The IRS’s older sample says you get a notice for each tax period you owe, but the past due amount to reinstate the agreement only has to be paid once.
I already made the payment. Do I still need to call?
The IRS’s page says yes: call so it has a record of what you did and can reinstate the agreement.
Can a CP523 affect my passport?
Only for large debts. In 2026, the IRS can certify a debt over $66,000 to the State Department once a lien is filed and appeal rights are used up, or a levy is issued. Debts being paid on time through an approved plan aren’t certified.
How do I know a CP523 is really from the IRS?
Check your plan and balance in your IRS Online Account, or call a number listed on irs.gov. Payment always goes to the United States Treasury. Our IRS letter decoder explains other codes too.
Sources
- IRS: Understanding your CP523 notice
- IRS: Payment plans, installment agreements
- IRS: Publication 1660, Collection Appeal Rights (PDF)
- IRS: Form 9423, Collection Appeal Request (PDF)
- IRS: Publication 594, The IRS Collection Process (PDF)
- IRS: Failure to pay penalty
- IRS: Revocation or denial of passport in cases of certain unpaid taxes
- IRS: Quarterly interest rates
The letter above is a made-up sample for learning, laid out like the IRS’s own CP523. It isn’t a real notice and nothing on this page reads or answers yours. Interest uses the IRS’s 2026 rates (6% in the second quarter, 7% from July). General education, not tax advice.