The short answer
If you’re a sole proprietor or a single-member LLC, you pay yourself with an owner’s draw: a simple transfer from your business account to your personal account. It isn’t a salary, nothing is withheld, and the draw itself isn’t taxed. You’re taxed on your business’s profit, whether you take the money out or not.
If you’ve elected S-corp status, it’s different: you must pay yourself a reasonable salary through payroll, with taxes withheld, and can take the rest as distributions.
How it works by business type
| Business type | How you get paid | Taxes withheld? | What you’re taxed on |
|---|---|---|---|
| Sole proprietor | Owner’s draw (a transfer) | No. You pay quarterly estimated taxes yourself | All business profit |
| Single-member LLC | Owner’s draw (same as above) | No | All business profit |
| LLC taxed as an S-corp | Salary through payroll, plus distributions | Yes, on the salary | Salary as wages; the rest of the profit as income, without self-employment tax |
The owner’s draw (sole proprietors and LLCs)
This trips up almost everyone at first: what you take out has nothing to do with what you’re taxed on. If your business earns $80,000 of profit and you only draw $50,000, you still owe tax on $80,000. If you draw $90,000 by dipping into savings, you’re still taxed on $80,000.
- A draw is not a business expense. You can’t deduct it.
- Nothing is withheld. That’s why you set aside 25 to 30% of every payment and pay the IRS quarterly.
- No payroll needed. Don’t put yourself “on payroll” as a sole proprietor or single-member LLC. You can’t be your own W-2 employee.
- Keep it clean. Move money from business checking to personal checking as a transfer, and label it “owner’s draw” in your books.
How much to pay yourself
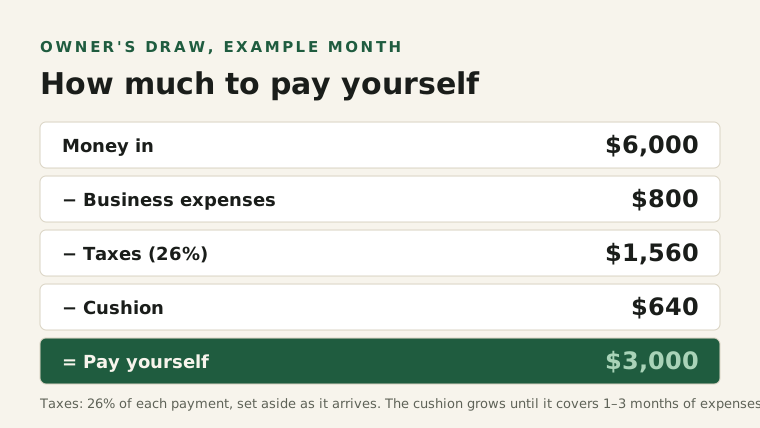
- Start with what came in this month.
- Subtract business expenses.
- Move 25 to 30% for taxes to your tax account, ideally as each payment arrives.
- Build a cushion in business checking until it covers 1 to 3 months of expenses, so a slow month doesn’t hurt.
- What’s left is yours.
Pay yourself on a schedule, like the 1st and 15th, not whenever you need money. If your income is lumpy, pay yourself a fixed “salary” you can sustain in a slow month, and let extra pile up in the business as your cushion. That one habit makes freelance income feel like a paycheck.
If you’re an S-corp: salary and distributions
Once your LLC is taxed as an S-corp, you’re an employee of your own company. The IRS says payments to an owner who works in the business must be treated as wages to the extent they’re reasonable compensation for the work.
- Salary: run it through a payroll service, with income tax, Social Security and Medicare withheld. Pay it on a regular schedule.
- Distributions: profit left after salary and expenses. These skip the 15.3% payroll tax, which is the whole point of an S-corp.
- “Reasonable” means market rate for the work you do, considering your experience, duties and hours. There’s no official percentage. The “60/40 rule” you’ll see online isn’t an IRS rule.
- A $0 salary with big distributions is the pattern the IRS looks for.
Not an S-corp yet? Here’s when it’s worth it.
Mistakes to avoid
- Paying personal bills straight from the business account. Transfer to personal first, then pay. Mixing money muddies your books and, for an LLC, weakens your liability protection.
- Spending the tax money. It isn’t yours. Move it out of reach the day it arrives.
- Draining the business every month. Leave a cushion so one late client doesn’t become a crisis.
- Thinking a smaller draw lowers your taxes. It doesn’t. Only lower profit does, through real business expenses. Here are the write-offs that count.
FAQ
Is an owner’s draw taxable? Not by itself. You pay income tax and self-employment tax on your business profit, which you report on Schedule C, whether you draw it or not.
Can I pay myself a salary as a sole proprietor? Not a real W-2 salary. You can pay yourself a fixed amount on a schedule, but it’s still an owner’s draw for tax purposes.
How often should I pay myself? Monthly or twice a month works for most people. Pick a schedule and stick to it.
Where should the money go? From business checking to your personal checking account. Here’s the simple 3-account setup.
Sources
- IRS: Wage compensation for S corporation officers (FS-2008-25)
- IRS: S corporation compensation and medical insurance issues
- IRS: Single-member limited liability companies
- Owner’s draw vs. salary: S-corp reasonable compensation
General education, not tax advice. If you’re an S-corp, set your salary with a tax professional.