Tap any line on the formHover over any line on the form to see what it means. Click a line to pin its note open so you can use the links. to see what it means. Our example is the one from the K-1 section below: a one-person consulting business, an LLC whose S-corp election took effect January 1, 2026. Clients paid it $120,000 and its other costs were $20,000, so it made $100,000 before your $50,000 salary. After salary and payroll taxes, its 2026 return shows $46,133 of ordinary business income, and you took $40,000 out as distributions. These are 2026 numbers on the 2025 form.


Swipe sideways to see the whole form.
Every line, in plain English
Tax year Calendar year or fiscal year
Almost every one-person S-corp uses the calendar year, and then you leave this line blank. You only fill in dates if the S-corp has a fiscal year approved by the IRS. Use the form for the year the tax year starts in.
ExampleYour S-corp runs January to December, so you leave it blank. For the 2026 tax year you'd use the 2026 form once the IRS posts it.
Item A S election effective date
The date your S-corp status started. It's on the CP261 notice the IRS sent when it accepted your Form 2553. It stays the same every year after.
ExampleYou enter 01/01/2026.
Our tipCan't find the CP261? The date you asked for on Form 2553, line E, is usually the same.
Item B Business activity code
A six-digit code for what the business mainly does, from the list of Principal Business Activity Codes at the end of the Form 1120-S instructions. Pick the one closest to how most of the money comes in.
ExampleA management consultant uses 541600, "Management, Scientific, & Technical Consulting Services."
Our tipIf you used a code on Schedule C before the election, it's usually the same one.
Item C Schedule M-3 box
Schedule M-3 is a long version of Schedule M-1 that S-corps with $10 million or more in total assets must file. Everyone else leaves this box empty.
ExampleYou leave it unchecked.
Name and address The S-corp's legal name and address
The company's name exactly as the IRS has it for its EIN, including "LLC" if it's an LLC, and the address of its main office. If the mail goes to your accountant, write "C/O" and their name on the street line.
ExampleYou enter the LLC's name and the address you use for the business.
Our tipMoved since last year? Check the address change box in item H. If you move after filing, tell the IRS with Form 8822-B.
Item D Employer identification number
The S-corp's own nine-digit EIN, not your Social Security number. Every S-corp needs one. If it doesn't have one yet, apply online at IRS.gov/EIN, where it's issued right away.
ExampleYou enter the LLC's EIN, the same one on your W-2 and Form 941s.
Item E Date incorporated
The date the business was created under state law. For an LLC taxed as an S-corp, that's usually the date the state accepted its formation papers, not the date the S election started.
ExampleYou enter the date your LLC was formed, which was before 2026.
Item F Total assets at year end
Everything the S-corp owned on the last day of the year: cash, receivables, equipment and so on, as your books show it. Enter 0 if there's nothing. If you fill in Schedule L, this is the same as Schedule L, line 15, column (d).
ExampleYour LLC started 2026 with $5,000 in its bank account and ended with $11,133, and it owns nothing else, so you enter $11,133.
Our tipYou fill this in even when Schedule B, question 11 lets you skip the balance sheet.
Item G Electing S-corp status starting this year?
Check Yes if this is the first tax year of your S-corp election. If you haven't filed Form 2553 yet, you attach it, but a Form 2553 sent in with the return is usually a late election. Check No in every later year.
ExampleYour election started January 1, 2026 and your Form 2553 is already accepted, so on the 2026 return you check Yes and attach nothing. From 2027 on, you check No.
Item H Final, name change, address change, amended, termination
Check a box only if one applies: this is the last return because the business is closing, the company changed its name or address, you're fixing a return already filed, or the S election ended this year.
ExampleNone apply, so you leave them blank.
Item I Number of shareholders
Everyone who owned shares at any point in the year. This number matters more than it looks: the late-filing penalty is charged per shareholder for each month the return is late.
ExampleYou're the only owner, so you enter 1. If your return were late, the penalty for 2026 returns would be $260 a month.
Item J Aggregated or grouped activities
For S-corps with several separate business activities that combine them for the at-risk or passive activity rules. A business with one activity leaves both boxes empty.
ExampleYour consulting work is one activity, so you leave them blank.
Line 1a to 1c Gross receipts or sales
Everything clients and customers paid the business for its work or products during the year (line 1a), minus refunds and discounts you gave back (line 1b). Line 1c is what's left. Rental income and investment income like interest don't go here: they go on Schedule K.
ExampleClients paid your S-corp $120,000 in 2026 and you refunded nothing, so lines 1a and 1c are $120,000.
Our tipCheck the total against your bank deposits and any 1099s the S-corp received.
Line 2 Cost of goods sold
The cost of products you sold, worked out on Form 1125-A. Service businesses usually have none.
ExampleYou sell your time, not products, so line 2 is blank.
Line 3 Gross profit
Line 1c minus line 2.
ExampleYours is $120,000.
Line 4 Gain or loss from selling business property
The result of selling or trading in something the business used, like a work car or equipment, from Form 4797, Part II. Most years this is empty.
ExampleYou didn't sell anything, so line 4 is blank.
Line 5 Other income
Business income that doesn't fit line 1a, with a statement listing each type. Examples from the instructions: interest you charge clients on late invoices, a bad debt you deducted before and later collected, and taxable insurance proceeds.
ExampleYou had none.
Line 6 Total income
Lines 3, 4 and 5 added together.
ExampleYours is $120,000.
Line 7 Compensation of officers: your salary
What the S-corp paid its officers, and in a one-person S-corp that's you. It's the salary you ran through payroll, plus health insurance the company paid for you, since you own more than 2%. It must be a reasonable salary for the work you do. Form 1125-E is only needed once total receipts reach $500,000.
ExampleYou enter $50,000, the salary on your 2026 W-2.
Our tipIf the S-corp paid your health insurance, it goes on this line too, and on your W-2. Distributions never go here.
Line 8 Salaries and wages for employees
Wages paid to employees who aren't officers. Your own salary is already on line 7, so in a one-person S-corp this is usually 0.
ExampleYou have no employees, so line 8 is blank.
Our tipPaying a contractor isn't wages. That goes on line 20 with your other costs.
Line 9 Repairs and maintenance
Fixing and maintaining business property, like repairing a laptop. Upgrades that add value or make something last much longer get depreciated instead, on line 14.
ExampleYou had none.
Line 10 Bad debts
Money owed to the business that you now can't collect. A cash-method business can't deduct an unpaid invoice, because that money was never counted as income in the first place.
ExampleOne client paid three months late but paid in full, so you have nothing here.
Line 11 Rents
Rent for business property, like an office or a leased car. The S-corp can't deduct rent on a home a shareholder lives in. For a home office, the usual route is to have the company reimburse you under an accountable plan.
ExampleYou work from home, so line 11 is blank. Your home office reimbursement is part of line 20.
Line 12 Taxes and licenses
Business taxes and fees, and for an S-corp that's mostly the company's share of payroll tax on your salary: 7.65% for Social Security and Medicare, plus federal and state unemployment tax. State business fees and licenses go here too. Federal income tax doesn't.
ExampleOn your $50,000 salary the company paid $3,825 of Social Security and Medicare and $42 of federal unemployment tax, so you enter $3,867. Our example leaves out state taxes and fees, which would go here too.
Our tipOnly the company's half goes here. The half withheld from your paycheck is already inside your $50,000.
Line 13 Interest
Interest on money the business borrowed for the business, like a business loan or a credit card used only for the business.
ExampleYour S-corp has no loans, so line 13 is blank.
Line 14 Depreciation
Depreciation on equipment and other property the business uses, from Form 4562. A section 179 deduction doesn't go here: an S-corp passes it through to you on Schedule K, line 11.
ExampleYou didn't buy any equipment in 2026, so line 14 is blank.
Our tipBought a computer and expensed it under section 179? Look for it on Schedule K, line 11, not here.
Line 15 Depletion
For businesses that use up natural resources, like timber. Oil and gas depletion isn't deducted here at all. Almost no one-person S-corp uses this line.
ExampleYou leave it blank.
Line 16 Advertising
Ads, sponsored posts, printed marketing and similar costs to promote the business.
ExampleYou had none. If you'd paid for a website ad, it would go here.
Line 17 Retirement plan contributions
What the company put into a retirement plan for its employees, including you, such as a Solo 401(k), SEP or SIMPLE IRA. With a Solo 401(k), the company can add up to 25% of your salary as an employer contribution.
ExampleYou didn't make one in 2026, so line 17 is blank. On your $50,000 salary, the company could have added up to $12,500.
Our tipA plan has to be set up the right way and on time for the deduction to count. Ask your tax pro before December.
Line 18 Employee benefit programs
Benefits like health insurance for employees who own 2% or less of the company. Your own benefits don't go here: as a more-than-2% owner, they're part of your pay on line 7.
ExampleYou have no employees, so line 18 is blank.
Line 19 Energy efficient commercial buildings
A deduction for making a commercial building more energy efficient, claimed on Form 7205. It's rare for a one-person business.
ExampleYou leave it blank.
Line 20 Other deductions
Every business cost that doesn't have its own line, with a statement listing each type and amount. The instructions give examples like insurance, legal and accounting fees, supplies, travel, 50% of business meals and utilities. Contractors and software usually land here too.
ExampleYour software, insurance, phone, accountant's fee and the home office costs the S-corp reimbursed you come to $20,000.
Our tipYour bookkeeping categories become this statement, so tidy categories save your tax pro time.
Line 21 Total deductions
Lines 7 through 20 added together.
ExampleYour total is $50,000 + $3,867 + $20,000 = $73,867.
Line 22 Ordinary business income
Line 6 minus line 21: the S-corp's profit from its business after your salary. It isn't taxed here. It passes to Schedule K, line 1 and then to your K-1, and you pay income tax on it on your own return. Unlike sole proprietor profit, it isn't subject to self-employment tax.
ExampleYours is $120,000 − $73,867 = $46,133.
Our tipDistributions don't reduce this number. You pay tax on the $46,133 whether you take it out or leave it in the business.
Line 23a Excess net passive income or LIFO recapture tax
Special corporate taxes that can apply when the S-corp used to be a C corporation, or merged with one tax-free. An LLC that went straight to S-corp status never owes them.
ExampleYou leave it blank.
Line 23b Tax from Schedule D
The built-in gains tax, figured on Schedule D (Form 1120-S). It also comes from a C corporation past, when the S-corp sells assets it owned as a C corporation.
ExampleYou leave it blank.
Line 23c Total tax
Lines 23a and 23b added, plus a few rare extras such as credit recapture from Form 4255. For most one-person S-corps this is 0, because the S-corp itself pays no federal income tax.
ExampleYours is 0. Your tax on the $46,133 is paid on your personal return.
Line 24a Estimated tax payments
Estimated payments the S-corp made toward its own taxes on line 23c, plus any overpayment from last year applied to this year. An S-corp only has to make these when those taxes are $500 or more. Your personal estimated taxes don't go here.
ExampleYour S-corp made none, so line 24a is blank.
Our tipYour quarterly payments on your share of the profit are made on Form 1040-ES, in your own name.
Line 24b Tax paid with Form 7004
Any tax the S-corp paid when it asked for an extension on Form 7004.
ExampleYou extended nothing, so line 24b is blank.
Line 24c Credit for federal tax on fuels
A credit for federal fuel tax on fuel used for certain purposes, like off-highway business use, from Form 4136.
ExampleYou leave it blank.
Line 24d Elective payment election amount
Certain clean energy credits can be taken as a payment instead of a credit. The amount comes from Form 3800. Rare for a small S-corp.
ExampleYou leave it blank.
Line 24z Total payments
Lines 24a through 24d added together.
ExampleYours is 0.
Line 25 Estimated tax penalty
A penalty if the S-corp should have made estimated payments for line 23c taxes and didn't, figured on Form 2220. Check the box if you attach that form.
ExampleYours is 0.
Line 26 Amount owed
If the S-corp owes tax, it's due by the original due date, even with an extension, and it must be paid electronically.
ExampleYour S-corp owes nothing, so line 26 is blank.
Line 27 Overpayment
If the S-corp paid more than its tax and penalty, the extra shows here.
ExampleYou leave it blank.
Line 28a and 28b Credit it forward or get it back
Split line 27 between next year's estimated tax (28a) and a refund (28b). The choice to apply it to next year can't be changed later.
ExampleYou leave both blank.
Lines 28c to 28e Direct deposit details
The S-corp's bank routing number (nine digits), whether it's checking or savings, and the account number (up to 17 characters). Use the business account, in the company's name.
ExampleNo refund, so you leave them blank.
Our tipIf the name on the account doesn't match the S-corp's name, the IRS mails a check instead.
Sign here Your signature as an officer
An officer signs and dates the return, such as the president or treasurer, and writes their title. The "May the IRS discuss" box lets the IRS call the paid preparer who signed below about the return.
ExampleYou sign as president. Your tax pro filed it, so you check Yes to let the IRS talk to them.
Paid preparer Your tax pro's details
Anyone paid to prepare the return signs here with their PTIN and firm details. If you prepare it yourself, or someone does it for free, leave it blank.
ExampleYour CPA fills this in.
Our tipThe 1120-S is a return we'd hand to a pro, at least in the first year.
Schedule B, 1 Accounting method
How the books count income and expenses. Cash means when money actually moves. Accrual means when you earn it or owe it. Most one-person S-corps use cash.
ExampleYou check Cash.
Schedule B, 2 Business activity and product or service
A few words describing the main activity and what you sell, matching the code in item B on page 1.
ExampleYou write "Consulting" and "Management consulting."
Schedule B, 3 Shareholders that aren't individuals
Yes if any shareholder during the year was a disregarded entity, a trust, an estate or a nominee. Then you attach Schedule B-1. If you own your shares in your own name, it's No.
ExampleYou own 100% yourself, so you check No.
Our tipIf you hold the shares through a living trust, this may be Yes. Ask your tax pro.
Schedule B, 4a Owning other corporations
Yes if, at year end, the S-corp owned 20% or more of another corporation directly, or 50% or more directly or indirectly. Then you list each one in the table.
ExampleYour S-corp owns no other companies, so you check No.
Schedule B, 4b Owning partnerships or trusts
The same question for partnerships, including LLCs taxed as partnerships, and trusts: 20% or more directly, or 50% or more directly or indirectly, of profit, loss or capital.
ExampleYou check No.
Schedule B, 5a and 5b Restricted stock and stock options
Whether the S-corp had restricted shares, stock options, warrants or similar outstanding at year end, and if so, how many shares. One-person S-corps almost never do.
ExampleYou check No for both and leave the share lines blank.
Schedule B, 6 Form 8918
Yes only if the S-corp filed, or must file, Form 8918, a disclosure that advisers make about certain tax shelter deals.
ExampleYou check No.
Schedule B, 7 Publicly offered debt
A box for corporations that sold bonds or other debt to the public at a discount. Not something a one-person business does.
ExampleYou leave it unchecked.
Schedule B, 8 Built-in gain from a C corporation past
Only for an S-corp that used to be a C corporation, or got assets from one, and still has untaxed gain from that time. It ties to the built-in gains tax on page 1, line 23b.
ExampleYour LLC was never a C corporation, so you leave it blank.
Schedule B, 9 Business interest election
Yes if a real estate or farming business has elected out of the limit on deducting business interest. Most S-corps check No.
ExampleYou check No.
Schedule B, 10 Form 8990, the business interest limit
Yes if any of a, b or c applies. Then you attach Form 8990. Item b only applies with average gross receipts over $31 million (the 2025 figure printed on this form; $32 million for 2026), so small S-corps answer No unless they own part of a partnership with excess business interest or are a tax shelter.
ExampleYou check No.
Schedule B, 11 The $250,000 test that skips two schedules
Yes if total receipts for the year were under $250,000 and total assets at year end were under $250,000. Then you don't have to fill in Schedule L, the balance sheet, or Schedule M-1. Total receipts means page 1, line 1a plus lines 4 and 5, plus income on Schedule K lines 3a, 4, 5a, 6, 7, 8a, 9 and 10, plus rental income from Form 8825.
ExampleYour receipts were $120,000 and your assets $11,133, so you check Yes and skip Schedules L and M-1.
Our tipSchedule M-2 on page 5 isn't covered by this, so it's still filled in.
Schedule B, 12 Canceled debt
Yes if a lender forgave, canceled or cut the principal of a debt the S-corp owed to someone other than a shareholder, with the amount on the next line. Forgiven PPP loans don't count.
ExampleYou check No.
Schedule B, 13 Subsidiary election ended
Yes only if a qualified subchapter S subsidiary election was ended or revoked this year. That takes owning a subsidiary corporation, which a one-person S-corp rarely does.
ExampleYou check No.
Schedule B, 14a and 14b Did you send the 1099s you owed?
Question 14a asks whether the S-corp made payments that required it to file any Form 1099, such as paying a freelancer $2,000 or more in 2026 ($600 before 2026). If Yes, 14b asks whether it filed them. Your own salary is on a W-2, not a 1099.
ExampleYour S-corp paid no contractors, so you check No on 14a and skip 14b.
Our tipIf you hired a contractor, send the 1099-NEC before filing so you can honestly answer Yes on 14b.
Schedule B, 15 Qualified Opportunity Fund
Yes only if the S-corp is certifying itself as a Qualified Opportunity Fund on Form 8996, an investment vehicle for certain low-income areas.
ExampleYou check No.
Schedule B, 16 Digital assets
Yes if the S-corp received crypto or another digital asset as payment or a reward, or sold, traded or otherwise disposed of one. Just holding it, moving it between your own wallets or buying it with dollars doesn't make it Yes. Don't leave it blank.
ExampleYour clients all pay by bank transfer, so you check No.
Schedule K, 1 Ordinary business income
The profit from page 1, line 22, carried here. Schedule K totals everything that passes through to the owners, and each owner's share goes on their K-1. As the only owner, your K-1 box 1 shows all of it, and you report it on Schedule E of your Form 1040.
ExampleYou enter $46,133, and box 1 of your K-1 shows $46,133.
Our tipThis is the number your personal return is waiting for. It's why the 1120-S is due a month before your 1040.
Schedule K, 2 to 3c Rental income
Rental real estate income or loss (line 2, from Form 8825) and other rental income and expenses (lines 3a to 3c). Rentals are kept apart from the business because different loss rules apply.
ExampleYour S-corp rents out nothing, so these are blank.
Schedule K, 4 to 10 Interest, dividends, gains and other income
Income that keeps its own character on your return: interest (4), dividends (5a and 5b), royalties (6), capital gains (7 to 8c), section 1231 gains from selling business property (9) and other items (10). Interest on the business savings account goes on line 4, not page 1.
ExampleYour business account paid no interest, so these are blank. If it had paid $50, line 4 would show $50.
Schedule K, 11 to 12e Section 179 and charitable gifts
Deductions that pass through to you instead of being taken on page 1: the section 179 deduction (11), charitable contributions (12a and 12b), investment interest (12c) and a few others. You claim them on your own return, subject to your own limits.
ExampleYou had none.
Our tipGave to charity from the business account? It goes here, not on page 1, and you deduct it personally if you itemize.
Schedule K, 13a to 13g Credits
Tax credits that pass through to you, like the low-income housing credit and other business credits, with a type and code for each.
ExampleYou had none.
Schedule K, 14a and 14b International items
Box 14a is for S-corps with foreign income, taxes or owners, which then file Schedule K-2 and give shareholders Schedule K-3. Box 14b is for one that qualifies for an exception to filing Schedule K-2, with a statement explaining why.
ExampleYour S-corp does all its work in the U.S. Your tax pro checks whether 14b applies.
Schedule K, 15a to 15f Alternative minimum tax items
Adjustments you'd need to figure the alternative minimum tax on your own return, mostly from depreciation and gains. Most one-person S-corps have none.
ExampleYou had none.
Schedule K, 16a to 16c Tax-exempt income and nondeductible expenses
Items that change your basis in the S-corp without showing up as taxable income: tax-exempt interest (16a), other tax-exempt income (16b) and nondeductible expenses (16c), such as fines and penalties.
ExampleYou had none.
Schedule K, 16d Distributions: money you took out
The total cash and property the S-corp paid you as the owner during the year, other than your salary. It's not a deduction and doesn't lower line 22. It shows in box 16 of your K-1, and it's generally tax-free as long as you have enough basis in the S-corp.
ExampleYou took $40,000 in owner draws during 2026, so you enter $40,000.
Our tipTook distributions? You'll usually attach Form 7203 to your 1040 to show your basis covers them.
Schedule K, 16e and 16f Loan repayments to you and foreign taxes
Line 16e is money the S-corp repaid you this year on loans you made to it. Line 16f is foreign tax it paid that you may be able to claim as a credit.
ExampleYou never lent the S-corp money and it paid no foreign tax, so both are blank.
Schedule K, 17a to 17c Investment income and old C corporation dividends
Investment income and expenses (17a and 17b), which you'd use for the investment interest limit, and dividends paid from earnings left over from C corporation years (17c), which go on Form 1099-DIV instead of the K-1.
ExampleYou had none.
Schedule K, 17d Other items, including your QBI details
A statement with other information you need, coded on your K-1. The one that matters most is code V: the details for your 20% qualified business income deduction, like the business's qualified income and the W-2 wages it paid. Your own salary isn't qualified business income, but it does count as W-2 wages.
ExampleYour statement shows $46,133 of qualified business income and $50,000 of W-2 wages.
Schedule K, 18 Income reconciliation
Lines 1 through 10 added, minus lines 11 through 12e and 16f. It must match Schedule M-1, line 8.
ExampleYours is $46,133, the same as line 1, because you had no other income or deductions.
Schedule L The balance sheet: start and end of year
What the S-corp owned and owed on the first and last day of the year, matching your books. Columns (a) and (b) are the start of the year, (c) and (d) the end. Skip it if you answered Yes to Schedule B, question 11.
ExampleYou answered Yes to question 11, so you leave all of Schedule L blank.
Our tipEven when it's optional, a balance sheet from your bookkeeping app makes the rest of the return easier to check.
Schedule L, 1 to 14 Assets
Cash (1), money clients owe you (2a and 2b), inventory (3), investments (4 to 9), equipment less depreciation (10a and 10b) and other assets. Line 7, loans to shareholders, is money the S-corp lent you.
ExampleIf your S-corp had to fill it in, line 1 would show $5,000 at the start of 2026 and $11,133 at the end, and everything else would be blank.
Our tipTook money out without calling it salary or a distribution? Sort it out with your tax pro before it lands on line 7.
Schedule L, 15 Total assets
All the assets added up, for both dates. The end-of-year figure in column (d) also goes in item F on page 1.
ExampleYours would be $5,000 and $11,133.
Schedule L, 16 to 21 What the S-corp owes
Bills it owes (16), loans and notes (17 and 20), other debts (18 and 21) and loans from shareholders (19), meaning money you lent the company.
ExampleYour S-corp owed nothing at either date.
Schedule L, 22 to 27 Shareholders' equity
The owner's side of the balance sheet: capital stock, paid-in capital, retained earnings and adjustments. Line 27 adds the liabilities and equity, and it must equal total assets on line 15.
ExampleWith no debts, your equity would equal your assets: $5,000 at the start and $11,133 at the end.
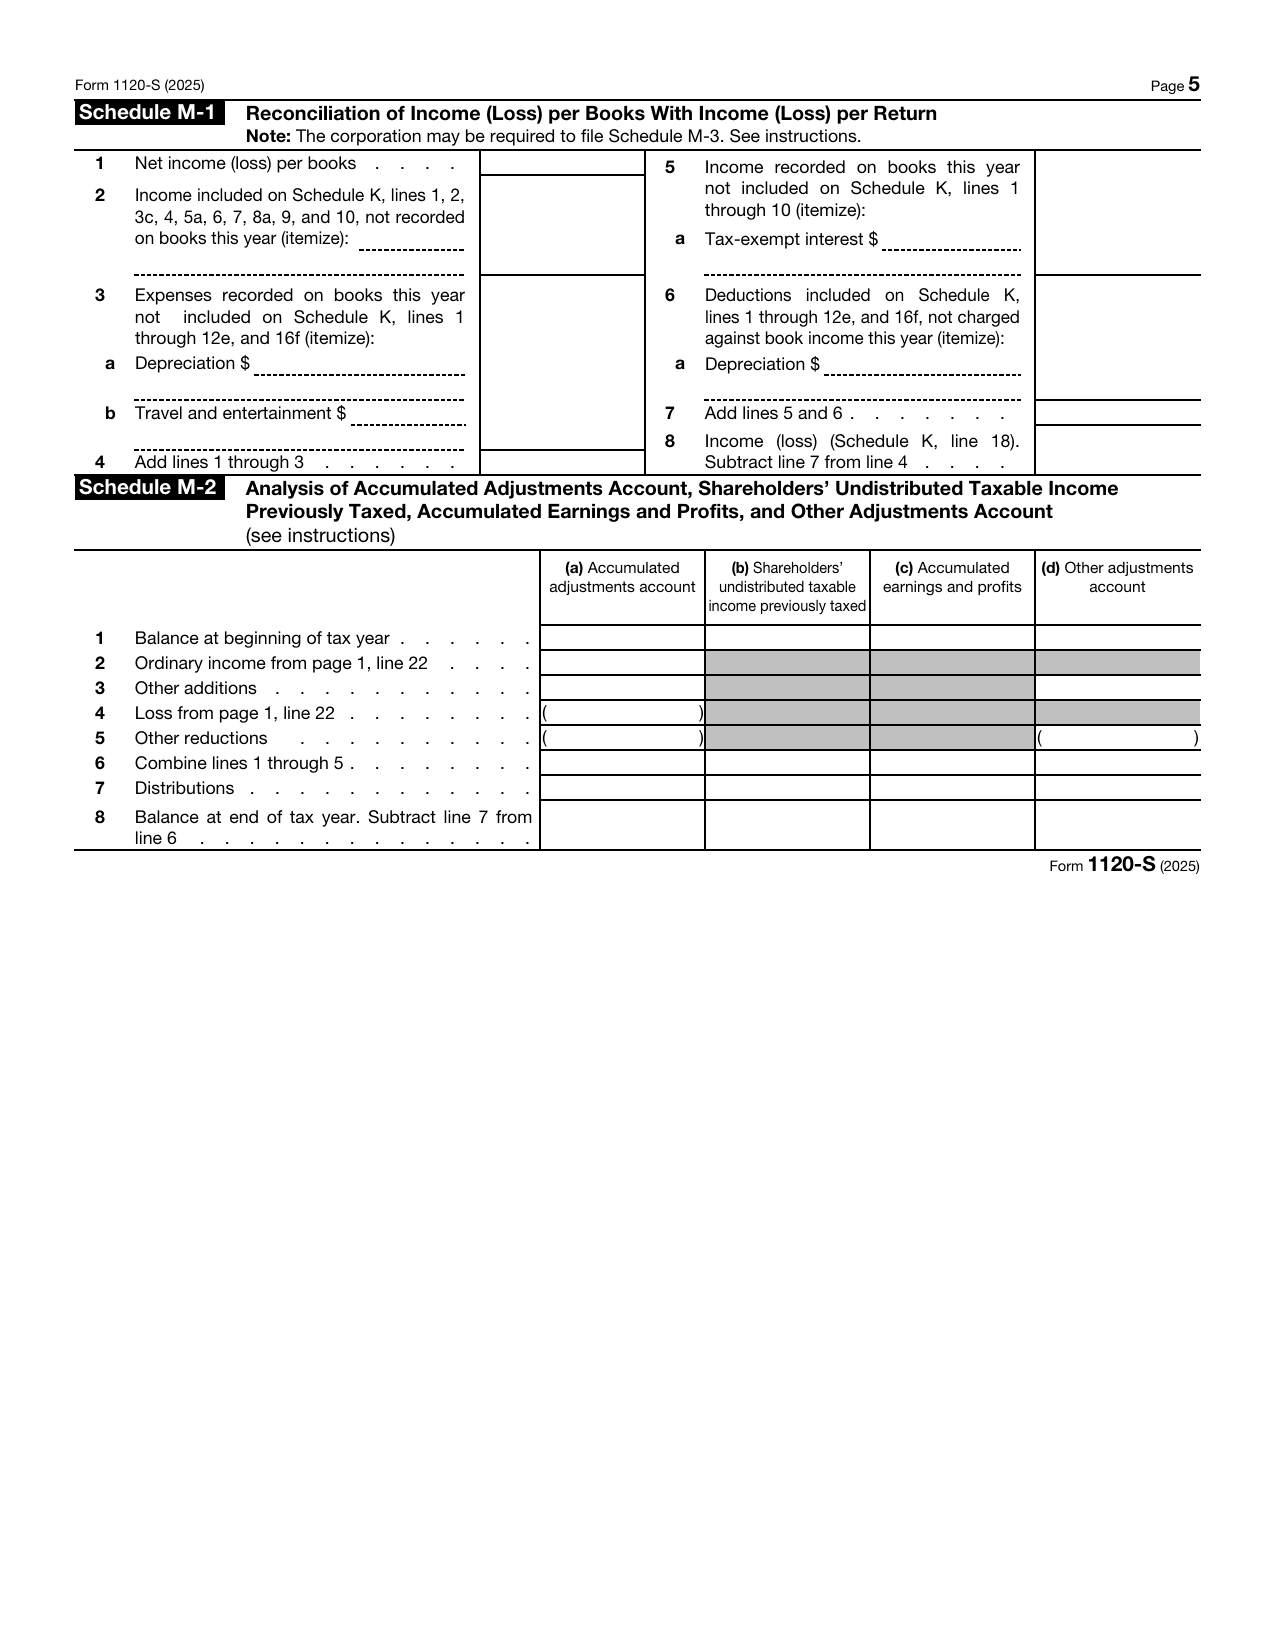
Schedule M-1, 1 Net income per books
The profit your bookkeeping shows for the year. Schedule M-1 explains any difference between that and the income on the return. Skip it if you answered Yes to Schedule B, question 11.
ExampleYou skip it. If you didn't, line 1 would be $46,133, because your books match the return.
Schedule M-1, 2 Taxable income not on the books
Income the return counts this year that your books don't, listed by type.
ExampleYou'd leave it blank.
Schedule M-1, 3 Book expenses the return doesn't deduct
Costs in your books that the return doesn't allow, such as extra book depreciation (3a) or travel and entertainment that isn't deductible (3b), like the nondeductible half of business meals.
ExampleIf $600 of meals were in your books, $300 would go on line 3b. Our example has none.
Schedule M-1, 4 Add lines 1 through 3
The subtotal for the left side.
ExampleYours would be $46,133.
Schedule M-1, 5 Book income the return doesn't tax
Income in your books that isn't on Schedule K lines 1 through 10, such as tax-exempt interest.
ExampleYou'd leave it blank.
Schedule M-1, 6 Deductions on the return, not the books
Deductions the return takes this year that your books don't, such as faster tax depreciation (6a).
ExampleYou'd leave it blank.
Schedule M-1, 7 Add lines 5 and 6
The subtotal for the right side.
ExampleYours would be 0.
Schedule M-1, 8 Income per return
Line 4 minus line 7. It must equal Schedule K, line 18.
ExampleYours would be $46,133, matching Schedule K, line 18.
Schedule M-2 columns Four running accounts
Column (a), the accumulated adjustments account (AAA), tracks profit the S-corp has earned and not yet paid out. Columns (b) and (c) only matter for old S-corps or ones that used to be C corporations. Column (d) tracks a few items, like tax-exempt income, that don't go in the AAA. Schedule B, question 11 doesn't let you skip this schedule.
ExampleYour S-corp only uses column (a).
Our tipThe AAA is the company's number. Your own basis, which decides whether distributions are tax-free, is tracked separately on Form 7203.
Schedule M-2, 1 Balance at the start of the year
Last year's ending balance from line 8. In the first year as an S-corp, the AAA starts at 0.
Example2026 is your first S-corp year, so line 1 is 0.
Schedule M-2, 2 Ordinary income from page 1
The profit from page 1, line 22, added to the account.
ExampleYou enter $46,133.
Schedule M-2, 3 to 5 Other additions, a loss and other reductions
Other income on Schedule K adds to the account (3). A loss from page 1 (4) and other deductions and nondeductible expenses (5) reduce it.
ExampleYou had none of these, so they're blank.
Schedule M-2, 6 Combine lines 1 through 5
The balance before distributions.
ExampleYours is $46,133.
Schedule M-2, 7 Distributions
What the S-corp paid out to owners this year, generally the same as Schedule K, line 16d. Distributions reduce the AAA, but not below zero.
ExampleYou enter $40,000.
Schedule M-2, 8 Balance at the end of the year
Line 6 minus line 7. It carries to line 1 on next year's return.
ExampleYours is $46,133 − $40,000 = $6,133, the profit you left in the business. It's also why your bank balance grew from $5,000 to $11,133.
