The short answer
When you work for yourself, nobody takes taxes out of your pay. You owe the same income tax as everyone else, plus a 15.3% self-employment tax that replaces the Social Security and Medicare your employer used to split with you. And you pay it yourself, four times a year.
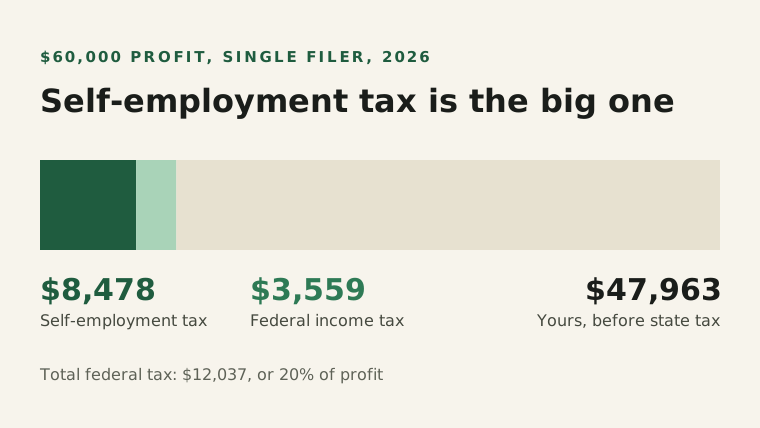
For a typical freelancer earning $60,000 in profit, that adds up to about $12,000 in federal tax, or 20% of profit. The biggest surprise for most people: at that level, self-employment tax is more than double their income tax.
The rest of this chapter shows exactly where that number comes from. Then Chapter 2 turns it into a percentage to set aside from every payment.
The two taxes you owe
1. Self-employment tax (15.3%). This is Social Security and Medicare for people who work for themselves.
- When you had a job, 7.65% came out of your paycheck and your employer quietly paid another 7.65%. Now you’re both, so you pay all 15.3%.
- It’s 12.4% for Social Security, on earnings up to $184,500 in 2026, plus 2.9% for Medicare, with no cap.
- It’s charged on 92.35% of your profit, not 100%. That’s the IRS’s way of giving you the same break an employer gets.
- You get to deduct half of it when you figure your income tax.
2. Federal income tax. The same brackets everyone pays, from 10% to 37%. It’s charged on your profit after:
- the standard deduction ($16,100 single, $32,200 married filing jointly, for 2026),
- half of your self-employment tax, and
- the 20% qualified business income (QBI) deduction, a big one most new freelancers don’t know they get.
Most states add their own income tax on top. A few, like Texas and Florida, don’t have one.
Worked example: a $60,000 freelancer
Maya is a freelance designer. In 2026 she bills $72,000 and spends $12,000 on software, a laptop and her home office, so her profit is $60,000. She’s single with no other income.
Self-employment tax
| Step | Amount |
|---|---|
| Profit | $60,000 |
| × 92.35% = net earnings from self-employment | $55,410 |
| Social Security: 12.4% | $6,871 |
| Medicare: 2.9% | $1,607 |
| Self-employment tax | $8,478 |
Income tax
| Step | Amount |
|---|---|
| Profit | $60,000 |
| − half of SE tax | −$4,239 |
| = adjusted gross income | $55,761 |
| − standard deduction | −$16,100 |
| − 20% QBI deduction | −$7,932 |
| = taxable income | $31,729 |
| Federal income tax (10% and 12% brackets) | $3,559 |
Total federal tax: $12,037, or 20% of her profit. Her self-employment tax is more than double her income tax.
As an employee earning the same $60,000 salary, her share of Social Security and Medicare would have been $4,590. Being her own employer costs her about $3,900 more in payroll tax. That’s the price of the freedom, and it’s why the write-offs in Chapter 5 matter so much.
Who counts as self-employed
If you earn money working for yourself, you’re self-employed for tax purposes, even if it’s a side gig. That includes:
- Freelancers and independent contractors paid on a 1099
- Consultants, coaches and creators
- Online sellers, Etsy and Amazon shops, and dropshippers
- Rideshare and delivery drivers
- Single-member LLCs that haven’t elected S-corp status
The $400 rule: if your net earnings from self-employment are $400 or more for the year, you owe self-employment tax and must file a return, even if you owe no income tax.
You owe tax whether or not you get a 1099. Clients only send 1099s above certain thresholds, and payment apps have their own rules. The IRS still expects you to report every dollar.
How you actually pay
During the year: quarterly estimated taxes. If you’ll owe $1,000 or more, you send the IRS four payments, due April 15, June 15, September 15 and January 15. Chapter 3 covers how much and how.
In April: your tax return. Along with your regular Form 1040, you file:
- Schedule C, which shows your business income and expenses and arrives at your profit.
- Schedule SE, which calculates your self-employment tax from that profit.
The quarterly payments you made get subtracted, and you pay or get back the difference. Tax software handles both schedules; Chapter 6 covers filing day.
The habit that makes it painless: move a percentage of every payment into a separate tax account the day it arrives. Chapter 2 tells you your number.
Myths that cost people money
“I’m in a low bracket, so I won’t owe much.” Self-employment tax is 15.3% starting from your first $400 of profit, regardless of your bracket. A $20,000 side business still owes about $2,800 of it.
“I didn’t get a 1099, so it’s not taxable.” All income is reportable, 1099 or not.
“An LLC lowers my taxes.” On its own, no. A single-member LLC is taxed exactly like a sole proprietor. It protects your personal assets, not your tax bill. The S-corp election is what can change your taxes (Chapter 7).
“Write-offs make things free.” A $1,000 business expense saves you roughly $230 to $320 in federal tax, not $1,000. Only spend on things the business actually needs.
FAQ
Do I pay self-employment tax on top of my W-2 job’s Social Security? Yes, on your side profit, until your combined earnings pass the $184,500 Social Security cap. Medicare applies to all of it.
Does self-employment tax count toward my Social Security benefits? Yes. It’s the same system, and it builds your future benefit just like payroll tax does.
Can I deduct half of my self-employment tax? Yes, automatically on your return. It lowers your income tax, not the SE tax itself.
Sources
- IRS: Self-employment tax
- IRS: 2026 tax inflation adjustments
- SSA: 2026 Social Security wage base
- IRS: Estimated taxes
General education, not tax advice. Numbers are 2026 federal figures.