How worried to be
It's a penalty bill, not a proposal, and it's charged even though the S-corp owes no tax. Pay by the date on the notice, or ask for relief if you have a reason.
When your reply is due
The IRS's usual window is 21 days from the notice date. Enter the date to see yours.
The IRS's CP162A page says to pay by the date shown on the notice to avoid more interest. In the IRS's own sample CP162, that date was 21 days after the notice date. Your notice prints yours, and that's the one that counts.
Tap any part of the letterHover over any part of the letter to see what it means. Click a part to pin its note open so you can use the links. to see what it means. Our made-up example: Sam Rivera's one-person S corporation, Harbor Lane Design LLC, filed its 2025 Form 1120-S on June 2, 2026, without an extension.
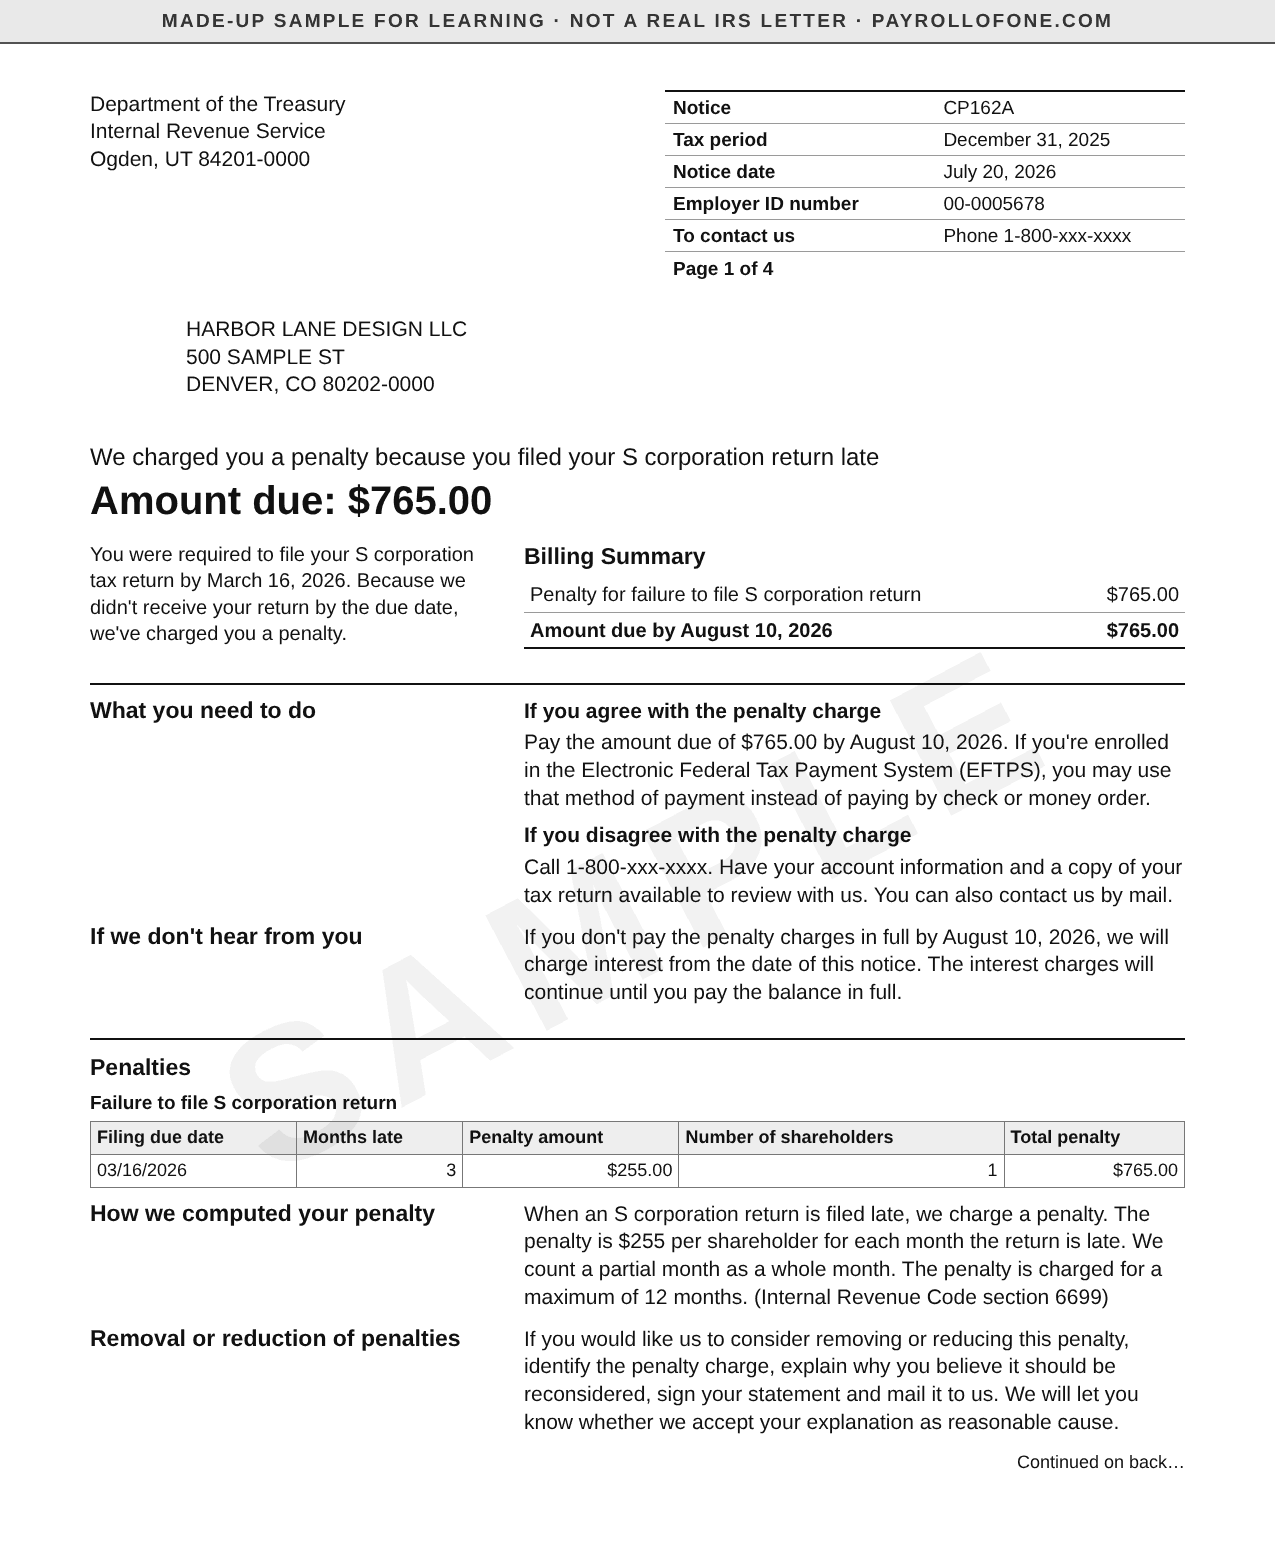
Swipe sideways to see the whole letter.
Every part, in plain English
Notice The notice code
CP162A is the IRS's penalty notice for an S corporation or partnership return filed late. It's part of the CP162 series: since 2022, the IRS's notice manual says a late Form 1120-S gets a CP162A, a return missing required information gets a CP162B, and the plain CP162 now goes to large partnerships that didn't file electronically.
ExampleType CP162A, CP162B or CP162 into our lookup and you land on this page.
Good to knowOlder IRS pages and samples still call the S corporation penalty notice a CP162. The penalty is the same one: a late or incomplete Form 1120-S.
Tax period Which return the penalty is for
The last day of the tax year the return covers. December 31, 2025 means the S corporation's 2025 Form 1120-S, the return due in March 2026.
ExampleHarbor Lane's penalty is for its 2025 return.
Good to knowA calendar-year S-corp's return is due the 15th day of the third month after the year ends. March 15, 2026 was a Sunday, so the 2025 return was due March 16.
Notice date The date the clock starts
The pay-by date counts from here. In the IRS's own sample CP162, the amount was due 21 days after the notice date. The notice also says that if the penalty isn't paid by then, interest runs from this date.
ExampleHarbor Lane's notice is dated July 20, 2026, and the amount is due August 10, 2026, 21 days later.
Good to knowEnter this date in the box above the letter to see the date 21 days later. The date printed on your notice is the one that counts.
EIN Your business's EIN
The Employer Identification Number of the S corporation. The penalty is charged to the S corporation under this number, not to you personally.
ExampleHarbor Lane Design LLC's made-up EIN is 00-0005678.
Good to knowCan't find your EIN paperwork? The IRS can confirm the number with a Letter 147C.
To contact us Who can call, and when
The number to call if you disagree. The IRS's CP162 page says that for a corporation, any officer authorized to sign for it can call, or anyone the chief officer authorizes with Form 2848.
ExampleSam, as the S corporation's officer, can call about Harbor Lane's notice.
Good to knowNot sure a letter is real? Call a number listed on irs.gov rather than one printed only in the letter.
Why Why the IRS charged a penalty
The reason line. This version, the CP162A, says the return was filed late. The CP162B says the return was missing required information, such as the Schedules K-1 or the balance sheet on Schedule L.
ExampleHarbor Lane filed its 2025 Form 1120-S on June 2, 2026, with no extension.
Good to knowIf a return is both late and incomplete, the IRS's manual says it charges only one of the two penalties: the incomplete-return one, unless the return is 12 months or more late.
Amount due A penalty with no tax behind it
The whole amount is penalty. An S corporation usually owes no income tax itself, but the late-filing penalty doesn't depend on tax owed. When an S-corp owes tax too, the IRS's manual says the penalty comes on a CP161 balance-due notice instead.
ExampleHarbor Lane owes no tax for 2025, and the penalty is still $765.00.
Good to knowIt's easy to miss: an S-corp that owes $0 with its return can still owe hundreds of dollars for filing it late.
The due date When the return was due
The date the IRS expected the return, and the reason for the penalty: it arrived after that. Without an extension, the due date doesn't move.
ExampleHarbor Lane didn't file Form 7004, so its deadline stayed March 16, 2026.
Good to knowForm 7004, filed by the original due date, gives an S-corp an automatic six months. For a 2025 return, that would have moved the deadline to September 15, 2026.
Amount due by Your pay-by date
The date to pay the full penalty. The IRS's CP162A page says to pay by the date shown to avoid more interest.
ExamplePaying $765.00 by August 10, 2026 settles Harbor Lane's notice.
Good to knowCan't pay it all? Pay what you can and ask about a payment plan.
If you agree Pay by the date
If the penalty is right and you have no grounds for relief, you pay it by the date on the notice, by check with the payment stub or through EFTPS.
ExampleIf Harbor Lane has no reason to ask for relief, it pays $765.00 by August 10, 2026.
Good to knowPaying now doesn't rule out relief later. Form 843, Claim for Refund and Request for Abatement, is how you ask in writing for a penalty to be removed.
If you disagree Call, with the return in hand
Call the number on the notice with your account information and a copy of the return, or write. Check the three numbers the penalty is built from: the due date, the months late and the number of shareholders.
ExampleIf Harbor Lane had mailed the return on time and kept proof, this is where it would say so. The IRS's CP162A page says to be ready to fax proof, such as a timely extension or proof of mailing.
Good to knowIf the shareholder count is wrong, the IRS's manual says it checks the number of Schedules K-1 filed and adjusts the penalty when they match what you say.
If you wait Interest from the notice date
If the penalty isn't paid in full by the pay-by date, interest is charged from the date of the notice until it's paid. That's different from interest on unpaid tax, which runs from the return's due date.
ExamplePaying by August 10 means Harbor Lane pays $765.00 and no interest.
Good to knowBy law, interest on a penalty drops only if the penalty itself is removed or reduced.
The math How the penalty adds up
Months late × the base amount × the number of shareholders. For returns due in 2026, the base is $255 for each month or part of a month, up to 12 months. Every person who owned shares at any time during the year counts. For returns due in 2027, the base rises to $260.
ExampleMarch 16 to June 2 is two full months and part of a third, so 3 months: 3 × $255 × 1 shareholder = $765.
Good to knowFor a one-owner S-corp, the most a 2025 return can cost is 12 × $255 = $3,060.
Relief Removal or reduction of penalties
The penalty doesn't apply if the late filing was due to reasonable cause, such as a disaster, serious illness or records you couldn't get. The IRS also lists the S corporation late-filing penalty as eligible for First Time Abate, for a business with a clean three-year record.
ExampleOur sample assumes Harbor Lane doesn't qualify for First Time Abate and Sam had no event like an illness or a disaster.
Good to knowFirst Time Abate doesn't cover the incomplete-return version of this penalty, and the IRS's manual says the small-partnership relief in Revenue Procedure 84-35 doesn't apply to S corporations.
